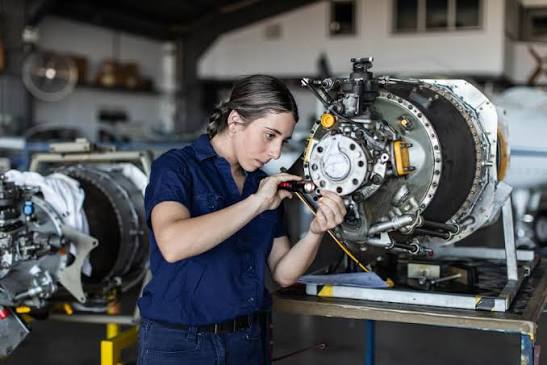
Europe's rising military budgets are creating a fast-growing market for mechanical and plant-engineering companies that traditionally served civilian industry. Germany's VDMA association says the opportunity extends well beyond weapons manufacturers because defence production depends on machine tools, automation, components, testing equipment and specialised manufacturing systems.
VDMA represents about 3,500 companies in Germany and elsewhere in Europe. Its survey found that 43 per cent of machinery firms already active in security and defence expect their related revenue to at least double by 2030, while another 46 per cent anticipate more moderate growth.
The near-term outlook is also strong. Almost one company in three already supplying defence expects sector revenue to rise by at least 15 per cent this year, and 92 per cent see room to increase deliveries during the next twelve months. Those figures indicate demand is running ahead of existing industrial participation.
Deputy Executive Director Hartmut Rauen said machinery makers should be able to gain significant market share. VDMA plans to support that move through matchmaking and market development, helping firms identify military customers, adapt products and enter supply chains that can be difficult for newcomers to navigate.
The industrial shift is not automatic. Respondents identified regulation, lengthy procurement procedures and insufficient contact with buyers as major barriers. Defence contracts also require security clearances, certification, traceability and long production commitments that differ from ordinary commercial sales and can impose substantial upfront costs.
The survey therefore exposes a gap between Europe's political spending pledges and its ability to convert money into equipment. Existing machinery capacity could accelerate output, but only if governments provide predictable orders, harmonise requirements and give smaller suppliers enough visibility to invest in workers and production lines.
The next test will be whether procurement reform advances as quickly as defence budgets. If access remains fragmented and slow, demand may concentrate among established primes. If barriers fall, Europe's machinery base could become a central part of rearmament while diversifying companies exposed to weaker civilian investment cycles.